Capital
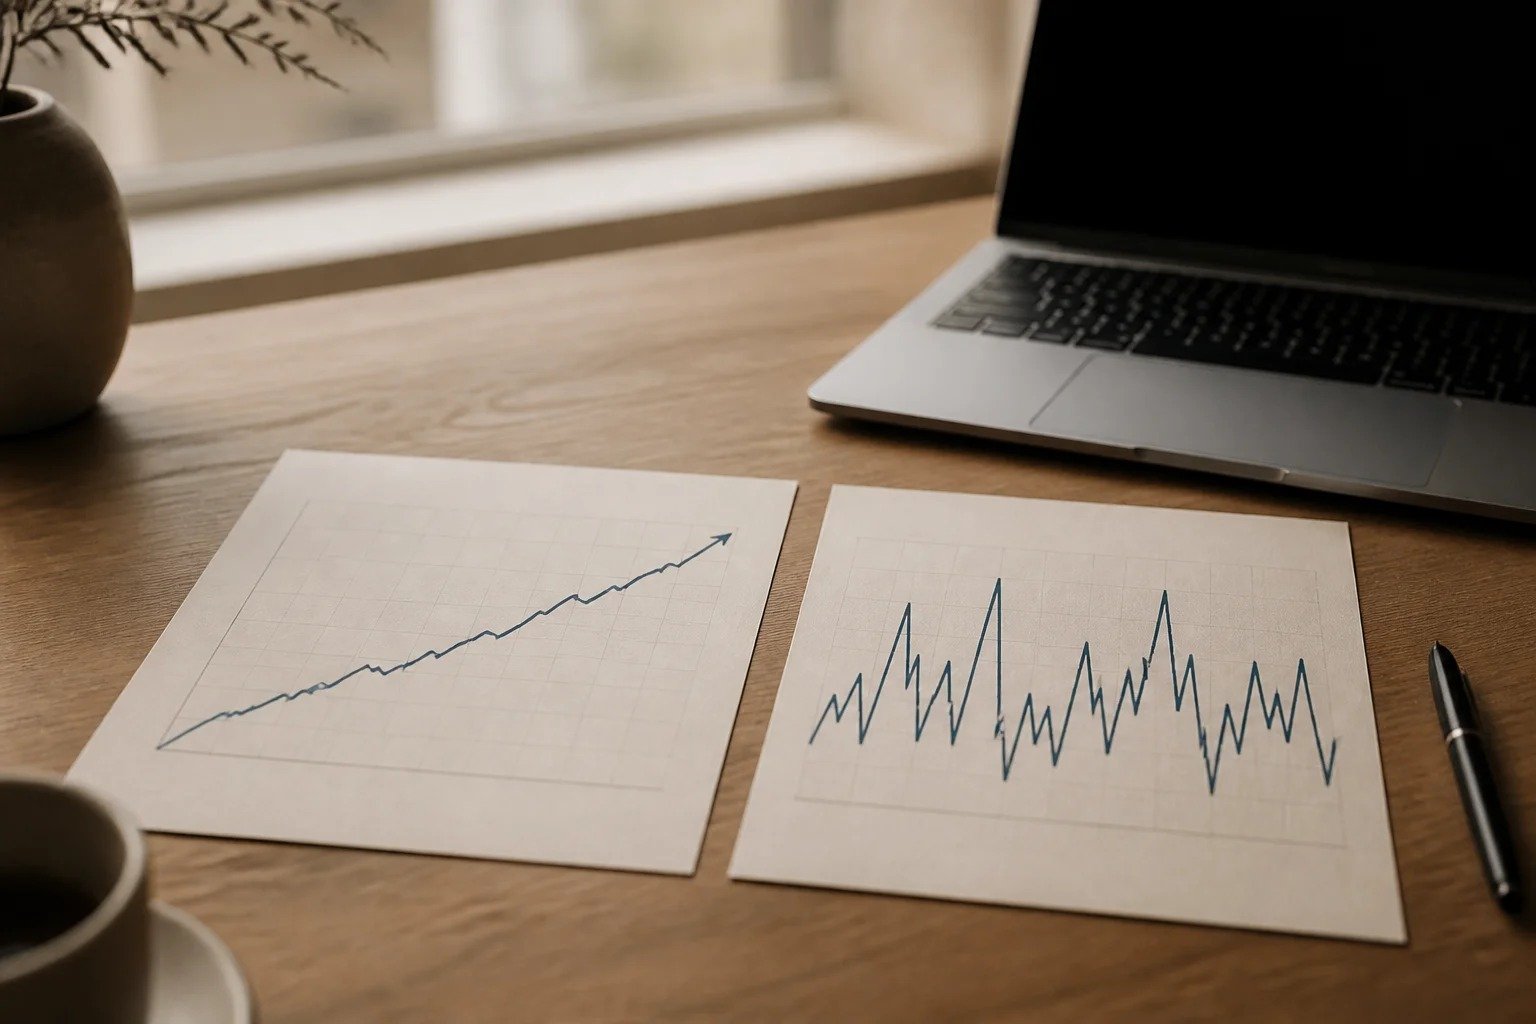
This isn’t really a debate anymore in terms of the data — it’s a debate about what people do with data they already know. Long-running independent scorecards comparing actively managed funds against their benchmark index have, across most periods studied, found that a clear majority of active managers underperform their index over ten-plus-year stretches, after fees. That’s not a hot take, it’s been a consistent finding for years.
What the long-run data actually shows
The consistent finding isn’t that active managers are bad at their jobs — many are genuinely skilled. It’s that beating a benchmark net of fees, year after year, for a decade or more, is extraordinarily hard to do consistently, and even funds that beat the market for a few years rarely keep doing it once you look at long enough time horizons. Past outperformance is a weak predictor of future outperformance at the fund level.
The scale is worth stating plainly, because “hard” and “85.6% of funds failed” land differently. In S&P Dow Jones Indices’ Year-End 2025 SPIVA U.S. Scorecard, 85.6% of actively managed large-cap funds underperformed the S&P 500 over the preceding ten years. Widen the window to twenty and it is 92.9%. Persistence is starker still: of the large-cap funds sitting in the top quartile for the twelve months to December 2021, none — 0.00% — were still in the top quartile four years later.
One caveat travels with those numbers, and it cuts against them. SPIVA counts a fund that closed mid-period as an underperformer and weights every fund equally rather than by assets, so it answers “what share of the funds you could have picked lost” rather than “what share of invested dollars lost.” Researchers who asset-weight instead put the twenty-year figure nearer 55%. That is a different measurement, not a rebuttal — and for someone choosing one fund off a list, the first question is the one that matters.
Why most active pickers underperform their own benchmark
Three structural reasons show up again and again: fees compound against you the same way returns compound for you, so a fund needs to beat the market by more than its expense ratio just to break even with an index. Trading costs from frequent buying and selling eat into returns in ways that don’t show up in a headline performance number. And behaviorally, most active investors — professional or amateur — sell winners too early and hold losers too long, which is a documented pattern, not a moral failing.
Where a genuine edge can still exist
None of this means picking stocks is irrational in every case. Real edges tend to come from information or attention most institutional analysis doesn’t prioritize — noticing a genuine shift in consumer behavior before it shows up in quarterly earnings, understanding a specific industry deeply enough to see a change coming, or simply having a longer time horizon than the market’s average participant. The edge is real but narrow, and it requires actual specific knowledge, not enthusiasm.
What this actually means for how you invest
For most of a portfolio, the data argues strongly for low-cost index funds as the default, not the consolation prize. That doesn’t mean never picking an individual stock — it means being honest with yourself about whether a specific pick is backed by a real information edge, or just conviction that feels like one. Sizing individual picks as a smaller portion of a portfolio, with the core sitting in index funds, is how you get to participate in both without betting the whole outcome on being right.
Run Your Life on Your Own Terms
The Keep — coffee, liberty, and capital, one email a week. No fluff, no spin.
Mei Lindqvist
Writes Capital on where individual investors actually have an edge over institutions — evidence-first, skeptical of expert-only framing, never a stock pick or a guarantee.
More like this: The Capital Guide indexes everything we have published in this pillar.